Personal and family goals
Meera, 42. For her family. And herself.
A homemaker in Chennai brings everyday savings, family priorities and personal ambitions into one clearer planning conversation.
- Age
- 42
- Starting point
- Homemaker
- City
- Chennai
An imagined story, with questions you might recognise. No customer results are being reported.
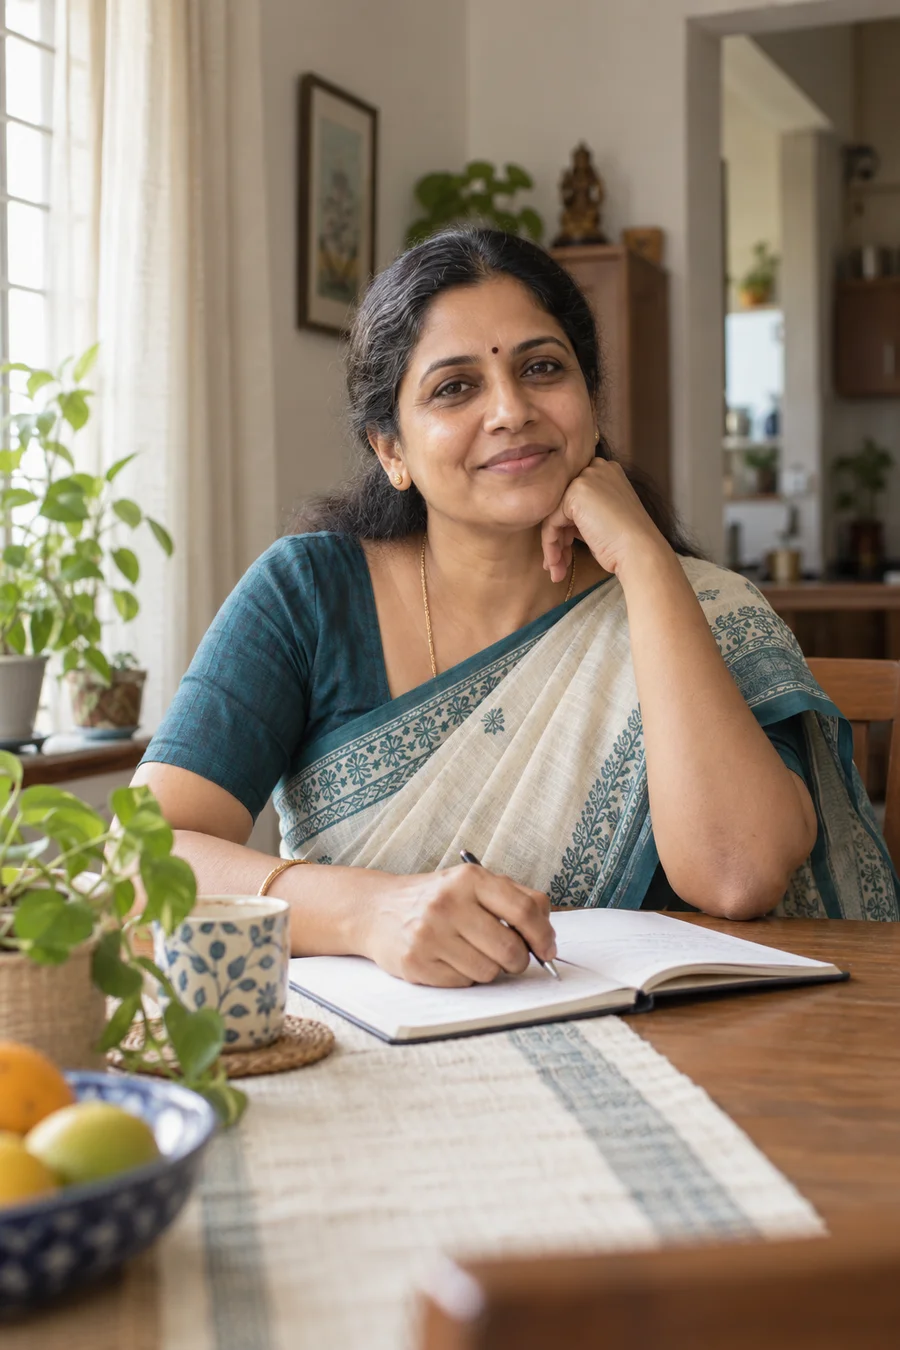
The person behind everyday decisions.
Meera, 42, knows the rhythm of her household in Chennai: what needs paying now, what can wait and what the family hopes to do next. She wants a clearer picture of the money set aside for those plans—and space for ambitions of her own.
She begins by bringing the available savings, regular commitments and account access into one conversation. Understanding the plan should belong to every decision-maker in the family.
Some money has a nearer purpose.
Meera explores a ₹1,00,000 FD for two years at an assumed annual rate of 6%, compounded quarterly. This lets her examine a defined timeline for a nearer expense. She would check the actual institution’s terms, interest payout and early withdrawal conditions before deciding.
Other goals have more time.
For a longer horizon, she models ₹3,000 a month over ten years using an 8% annual return assumption. She can use the SIP calculator to try smaller contributions or different return assumptions and understand the difference.
The example does not select a mutual fund, assess suitability or establish that a goal is funded. Actual returns fluctuate, may be negative, and are affected by costs and taxes. Family goals such as education also need their own future-cost estimate after inflation.
A plan she can participate in.
- Write down personal goals alongside family priorities.
- Check who owns and can access the savings.
- Understand nomination arrangements and account documents.
- Revisit timelines and affordability when circumstances change.
The goal calculator is a way to explore time, inflation and existing savings separately. It gives Meera a starting point for questions, while her decisions remain her own.
Clear assumptions. Space to decide.
Meera is an imagined person. Her story gives these questions a familiar setting; it doesn’t report customer results or recommend an investment. The numbers below are starting points she could explore.
Make the assumptions visible
What could the numbers look like?
Separate examples, with separate timelines.
Calculated using Finbharat’s FD and SIP tools.
Fixed deposit example
A defined timeline.
- Deposit amount
- ₹1,00,000
- Time horizon
- 2 years
- Assumed annual rate
- 6%
- Compounding
- Quarterly
Estimated maturity value
- Original deposit
- ₹1,00,000
- Estimated interest
- ₹12,649
Sample rate, not a deposit offer. Check actual institution and withdrawal terms.
Try your own assumptionsMutual fund / SIP example
A longer view.
- Monthly contribution
- ₹3,000
- Time horizon
- 10 years
- Assumed annual return
- 8%
Estimated future value
- Total contributions
- ₹3,60,000
- Estimated growth
- ₹1,92,497
Constant return assumed; actual returns fluctuate and may be negative. Contributions assumed at the start of each month.
Try your own assumptionsThese numbers show one possible set of assumptions. Taxes, fees, inflation and early withdrawal costs aren’t included. They don’t show what a customer earned or confirm that a goal is funded. Your circumstances and investment choices will shape your own plan.
Explore your goal