Planning with variable income
Arjun, 42. Every trip. A little more possibility.
An auto driver in Bengaluru explores savings for quieter days and small regular contributions toward a longer-term goal.
- Age
- 42
- Starting point
- Auto driver
- City
- Bengaluru
An imagined story, with questions you might recognise. No customer results are being reported.
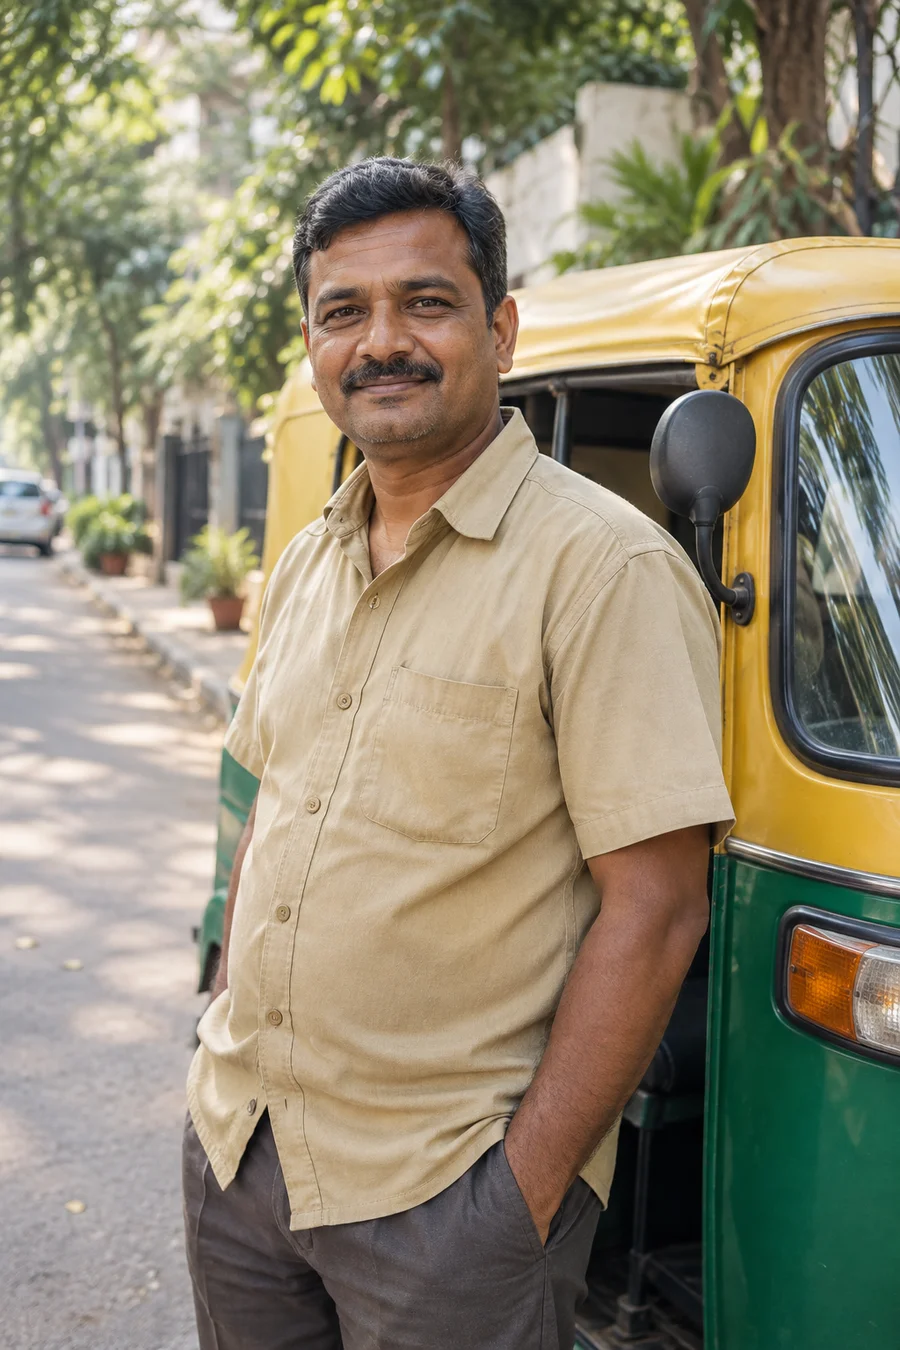
A working day does not always earn the same amount.
For Arjun, a 42-year-old auto driver in Bengaluru, a busy day and a quiet day can look very different. Fuel, repairs and household bills don’t follow the same rhythm. He wants to set money aside in a way that leaves room for both.
He first looks at what remains after those costs. Before choosing an investment amount, he wants an access plan for quieter days, repairs and unexpected expenses.
Understand when saved money can be used.
Arjun explores a ₹50,000 fixed deposit over one year at an assumed 6% annual rate, compounded quarterly. Seeing the deposit and estimated interest separately helps him understand what the money could do over that year. An actual decision would depend on the institution’s terms and his ability to leave that money deposited.
He would check early withdrawal rules rather than assume a deposit is available immediately without a cost. His day-to-day buffer and a defined-tenure deposit can have different jobs.
Small contributions need to fit real cash flow.
For a longer-term goal, he models ₹2,000 a month over ten years using an 8% annual return assumption. The example assumes the same contribution every month; it does not model changing earnings, missed contributions or actual market movements.
He can try a smaller amount in the calculator and think about what remains affordable in a quieter month. A SIP does not guarantee returns, and a mutual fund’s value can fall. Risk, suitability and costs need to be understood before investing.
- Account for fuel, maintenance and essential spending first.
- Keep a practical access plan for interruptions to earnings.
- Try contribution amounts that fit quieter months too.
- Review the plan when work or family commitments change.
One useful conversation at a time.
Arjun is an imagined person with a familiar challenge: planning ahead when income changes. This story explores possible choices, not investments he made or results he achieved. The sample calculations below exclude taxes, fees, inflation and early withdrawals. They are not proof that a future goal is funded.
Make the assumptions visible
What could the numbers look like?
Separate examples, with separate timelines.
Calculated using Finbharat’s FD and SIP tools.
Fixed deposit example
A defined timeline.
- Deposit amount
- ₹50,000
- Time horizon
- 1 year
- Assumed annual rate
- 6%
- Compounding
- Quarterly
Estimated maturity value
- Original deposit
- ₹50,000
- Estimated interest
- ₹3,068
Sample rate, not a deposit offer. Check actual institution and withdrawal terms.
Try your own assumptionsMutual fund / SIP example
A longer view.
- Monthly contribution
- ₹2,000
- Time horizon
- 10 years
- Assumed annual return
- 8%
Estimated future value
- Total contributions
- ₹2,40,000
- Estimated growth
- ₹1,28,331
Constant return assumed; actual returns fluctuate and may be negative. Contributions assumed at the start of each month.
Try your own assumptionsThese numbers show one possible set of assumptions. Taxes, fees, inflation and early withdrawal costs aren’t included. They don’t show what a customer earned or confirm that a goal is funded. Your circumstances and investment choices will shape your own plan.
Explore your goal